// For buyers
Buying in Snohomish County, without the guesswork.
More inventory, longer days on market, and rates near 7.4% mean buyers have choices and leverage they have not had in years. The key is in the strategy: terms, timing, and knowing your real buying power going in.
// Free resource
The Snohomish County Buyer Guide
A plain-English guide to buying a home in Snohomish County, from financing to closing.
The five-step process
Define the move, not just the house
What actually needs to change: space for the kids, a shorter commute, a better school boundary, a neighborhood that fits your life. The house follows the reasons.
Get your numbers with a lender
Curt partners with lenders he trusts. Pre-underwriting before you shop tells you your real buying power, including what your current equity can do for you.
Shop the right areas
A shortlist built on data: schools, commute, resale history, and the feel of each community. He can point you to the Snohomish County towns that match your criteria.
Make a strong offer
In a market where inventory is up but rates are high, the winning offer is about terms, not just price: inspections, timelines, and contingencies handled smartly.
Inspect, negotiate, close
The inspection is where a builder’s background earns its keep. Curt reads the report with you, separates real issues from noise, and negotiates repairs that matter.
The review clients keep repeating: "Curt explained what made sense and what didn't, and never pressured us into a decision." Buying this way is calmer, and it ends with a better house.
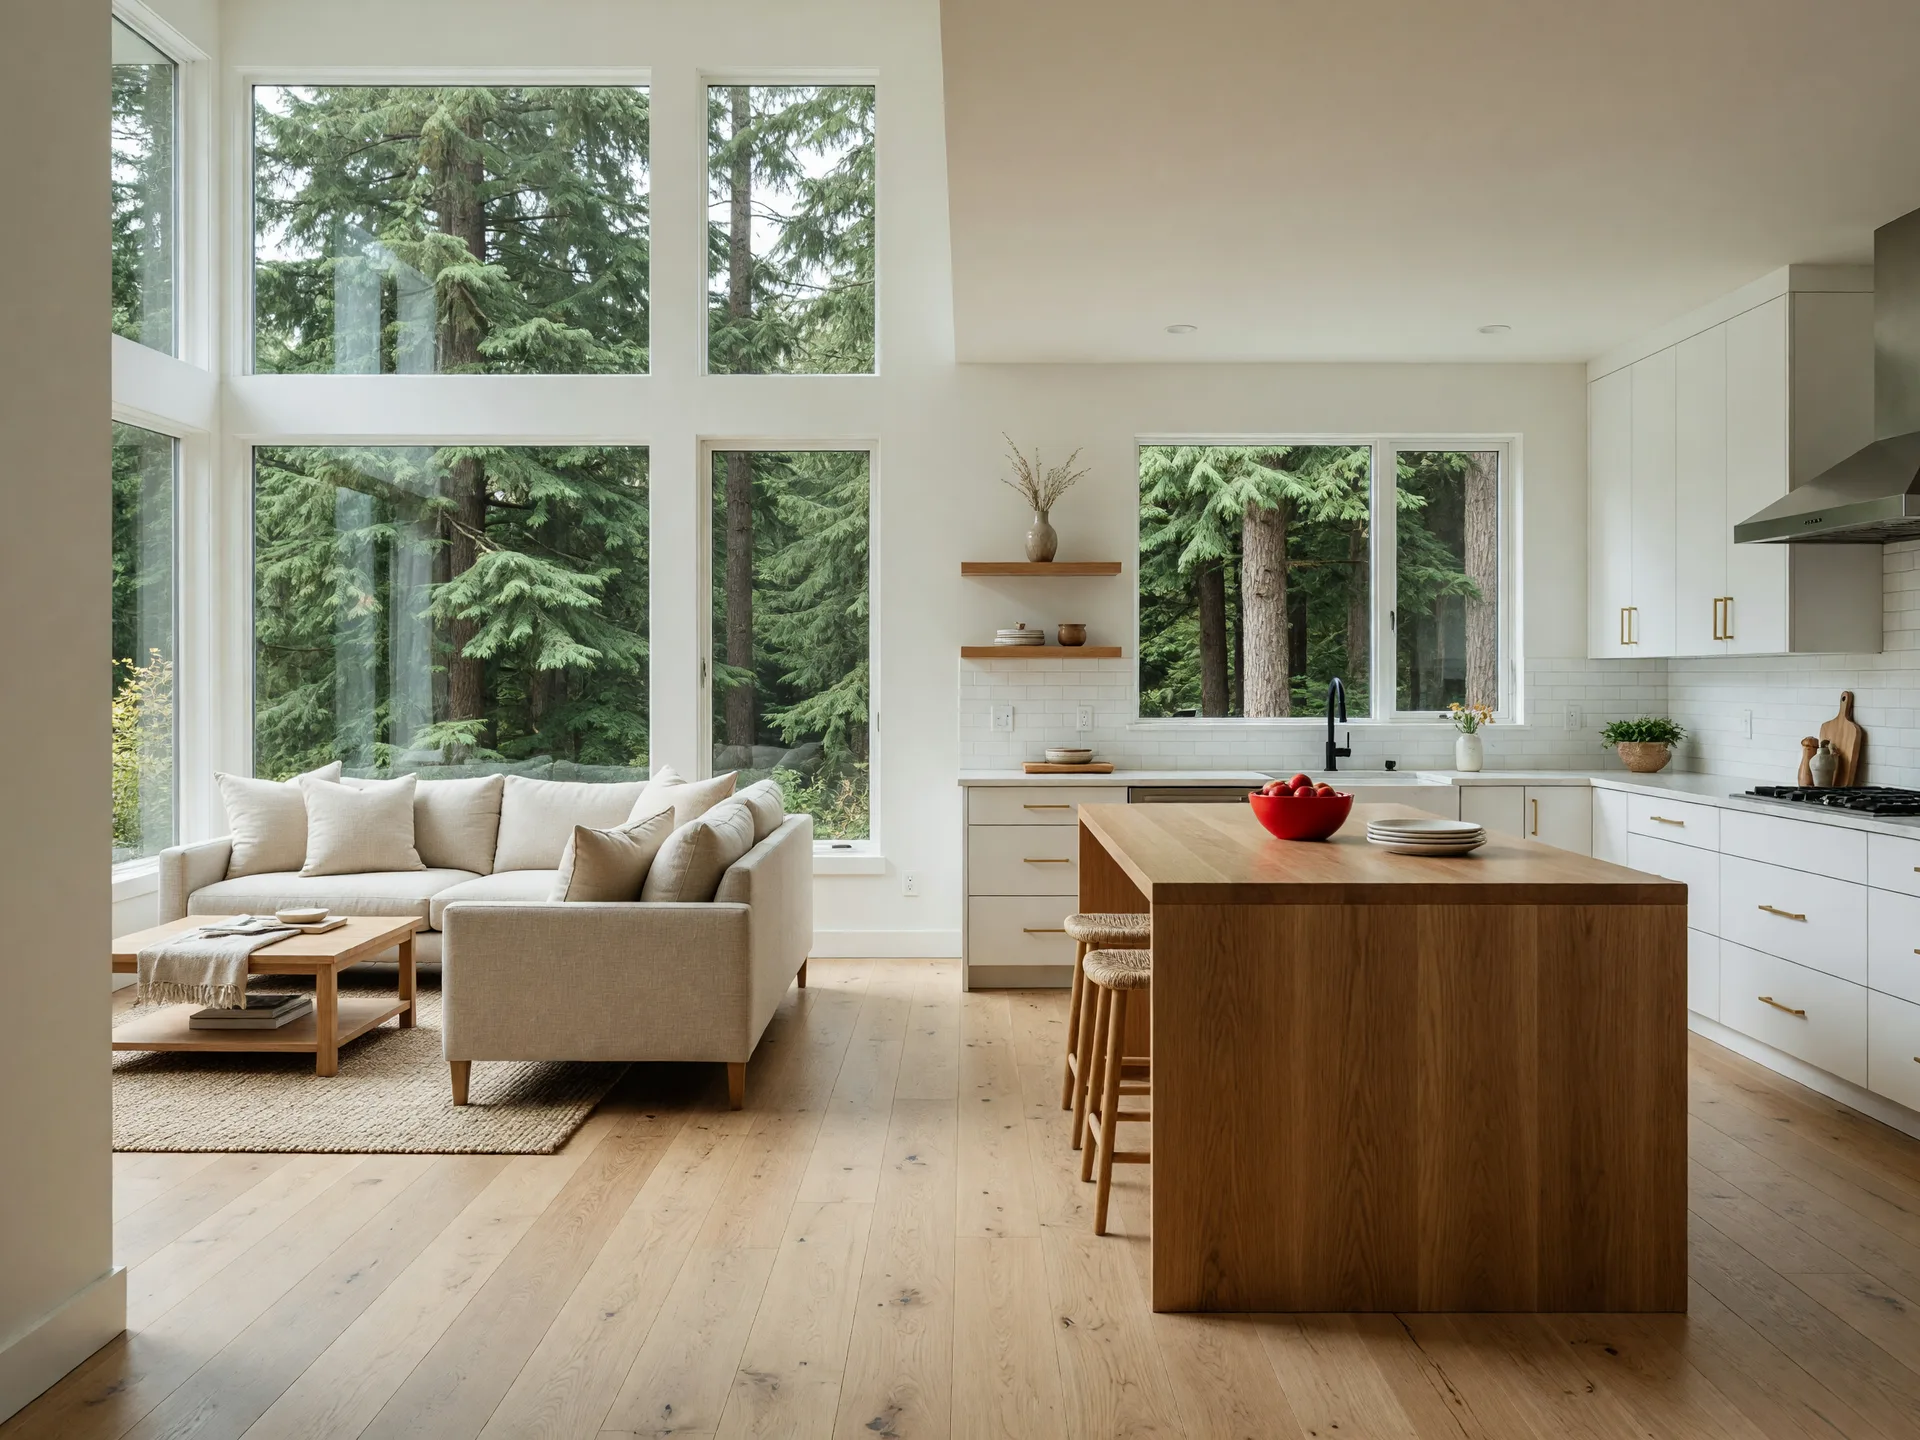
The right layout for the next stage of life
Rates in plain English
Washington 30-year fixed rates started 2026 near 6% and sit around 7.4% in October, per Freddie Mac's Primary Mortgage Market Survey for the week of October 15, 2026. Higher rates press budgets, but they also cool competition. Your real lever is equity: most move-up buyers in this county have far more than they realize.
Related: how much equity do you need? Related: giving up a 3% rate// For move-up buyers
Buying before you sell: four ways to make it work.
Sell first, then buy
The strongest position: cash in hand, no contingency. A short rental or negotiated rent-back bridges the gap between closings.
Buy first, then sell
Uses a bridge loan, HELOC, or lender qualification on both payments so you never lose the house you want. Carries two payments for a defined window.
Contingent offer
Make your offer contingent on your current home selling by a date. Less competitive, but viable in today’s balanced market, and zero double payments.
Simultaneous close
Both closings scheduled days apart with rent-back flexibility, the classic move-up sequence, and the one Curt coordinates most often.
The right option depends on your equity, your timeline, and your appetite for risk. Curt has coordinated all four, including bridge loans with lenders who know how to move fast.
// First time in the market?
Start with the First-Time Buyer Hub.
Down payment assistance through the Washington State Housing Finance Commission, a county program that can offer up to $50,000 in help, and a step-by-step walkthrough of what buying actually costs beyond the price tag.
Next step: a 30-minute consult
Tell Curt where you want to live and roughly what you can spend. You will leave with a shortlist of communities, a realistic price range, and a clear plan for buying, selling, or both.